 A Nation Must Think Before it Acts
The Ring of Global Compute and the Limits of Chip Export Controls

A nation must think before it acts.
The Ring of Global Compute and the Limits of Chip Export Controls
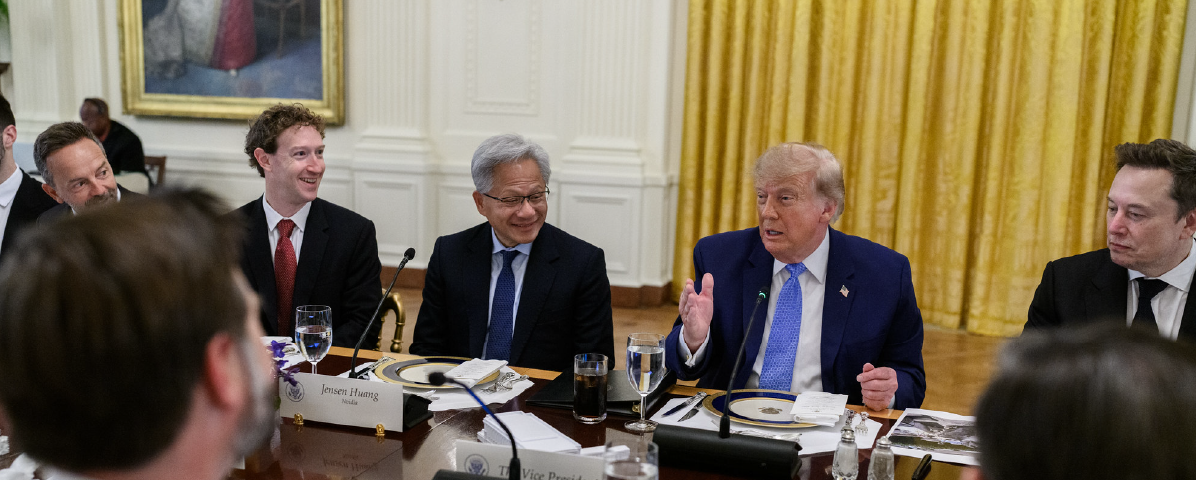
The scandal embroiling Jensen Huang, the former chief executive officer of Nvidia, has become nothing less than “Jensanity,” a global wave of celebrity adulation for the co-founder of the company behind the world’s AI infrastructure. For Huang, the massively lucrative Chinese market was much like J.R.R. Tolkien’s “One Ring”: once slipped on, it proved nearly impossible to remove, compelling him to do whatever it demanded to preserve market domination. Huang spent years meticulously tending to government relations from Washington to Taipei and to Beijing. As the world’s finest “chip diplomat,” Huang clearly understood the value of becoming a welcome partner in every capital across rival jurisdictions with an eye to continuing to sell Nvidia’s processors to China. On November 12, that balancing act collapsed with Huang’s abrupt resignation after reports of an affair with Alice Huang, a former executive at Singapore-based cloud partner Megaspeed whom US intelligence officials reportedly suspected of aiding Beijing. While official probes remain ongoing and unresolved, Huang’s network allegedly channeled or leased roughly 240,000 restricted Nvidia chips worth $7.5 billion toward Chinese users. From Congress to corporate boardrooms, debate continues over how controls were bypassed. How the control of the chokepoint of critical chips can be manipulated will be of strategic interest for US economic security moving forward.
Advanced semiconductor trade and production cannot simply be turned on and off, as global tech industries have spent decades developing a sprawling, multi-tiered web of third-party suppliers known as the Original Equipment Manufacturer (OEM) model. Chip designers such as Nvidia do not ship chips directly to end users. Instead, processors move from Taiwanese foundries such as TSMC to server integrators such as Supermicro, then to regional distributors and cloud operators such as Megaspeed. Centralizing “bill-to” invoicing in hubs such as Singapore while dispersing physical server deliveries across Asia obscure the flow of supply chains. More importantly, commercial incentives widen those cracks, which are the very dynamic behind Huang’s vision of domination. Because chipmakers and server vendors profit from hardware volume and software ecosystem lock-in, they face weak incentives to audit lucrative downstream buyers beyond baseline compliance paperwork. Jurisdictional divergence compounds the challenge: while transit hubs such as Singapore and Malaysia prosecute domestic customs fraud, they decline to enforce unilateral foreign export bans. The biggest challenge, though, may be that compute itself is borderless, allowing overseas data centers to rent AI processing power over fiber-optic cables without crossing physical custom checkpoints. Simply put, a deeply interlocked global commercial web defies the neat theory of a semiconductor chokepoint. There are always loopholes.
Chinese firms have actively exploited these loopholes into a three-part circumvention playbook. First, there is offshore corporate layering and transshipment. Newly incorporated intermediaries or shell companies in Singapore and Malaysia secure cloud-partner status to buy server racks housing restricted Nvidia chips; Megaspeed’s Malaysian unit Speedmatrix alone imported roughly $4 billion in Nvidia-equipped hardware. Second is nested offshore cloud leasing, or “compute-as-a-service,” which can bypass both US export bans and Beijing’s own regulatory curbs on importing downgraded foreign chips into mainland data centers. Keeping restricted processors legally bolted into racks across Southeast Asia or Japan, these intermediaries rent raw computing capacity to brokers serving Chinese giants such as Tencent and Alibaba without generating actual export manifests of those processors. Third, mainland buyers often mix legal and illicit hardware inside the same workflows through reserving scarce, smuggled H100 chips for heavy model training while running routine tasks on legally imported, downgraded Nvidia processors. This is common practice, as even blacklisted defense-linked Chinese universities can openly purchase restricted chips through local Chinese middlemen, who, lacking overseas accounts, remain insulated from the US jurisdiction while complying fully with the Chinese law.
The Huang saga should tighten these vulnerabilities. Regulators and lawmakers are moving to ban Chinese firms from remotely renting advanced chips overseas and to require export licenses for shipments into hubs such as Malaysia and Singapore. Meanwhile, corporate self-preservation is kicking in before new laws even take effect, best exemplified by Oracle abruptly canceling a $7 billion Southeast Asian chip-leasing deal with Tencent. Similarly, Chinese AI developers are also scrambling in response, from racing to lock in remaining overseas compute leases to stockpiling gray-market chips domestically, and from restructuring offshore shells below 50 percent affiliate ownership to shifting compute hosting toward less-scrutinized jurisdictions beyond traditional hubs. All of these are intended to evade looming subsidiary blacklists.
Questions abound about how upcoming export rules will unfold or how tightly they can be enforced. Meanwhile, rising barriers are already accelerating the very outcome chokepoint strategists have sought to prevent: a forced migration off Nvidia’s proprietary CUDA software ecosystem, its strongest lock on developers, toward a homegrown Chinese supply chain. Unable to match Nvidia chip-for-chip without advanced chipmaking tools, Chinese firms are compensating on two fronts: hardware scale and software efficiency. On the hardware side, Huawei wires thousands of its newer Ascend 950 and 960 processors, paired with emerging domestic AI memory from ChangXin Memory Technologies, into its Atlas SuperPoD systems so they function as a single supercomputer. On the software side, scarcity has pushed Chinese labs whose operations have long centered with algorithmic efficiency to further streamline model architectures and slash computing costs, squeezing frontier performance out of constrained processors. This shift is underscored by DeepSeek’s V4 debut in April, which prompted major Chinese enterprises to move everyday AI workloads onto domestic options.
Regardless of how the new export rules eventually roll out, China won’t be holding back. Backed by state capital and Beijing’s counter-leverage over critical minerals, Chinese firms are moving from opportunistic smuggling toward self-reliance building. Stricter enforcement after Huang’s exit will make advanced chips costlier and harder for Chinese firms to obtain, yet it illustrates the core paradox of chokepoint statecraft: when squeezing a global market hard enough, determined rivals will simply build their own, splitting the AI world into two competitive camps. In such a fractured world, Western firms can only keep their lead if they innovate faster, execute sharper, and scale more efficiently than ever before.
The author’s views expressed here are personal and do not reflect the official policy or position of the Department of the Army or any US government entity.
Image: Flickr | The White House